🌎 Fervo flips the switch #316
Our Q&A with Fervo COO after Cape Station commercial operation
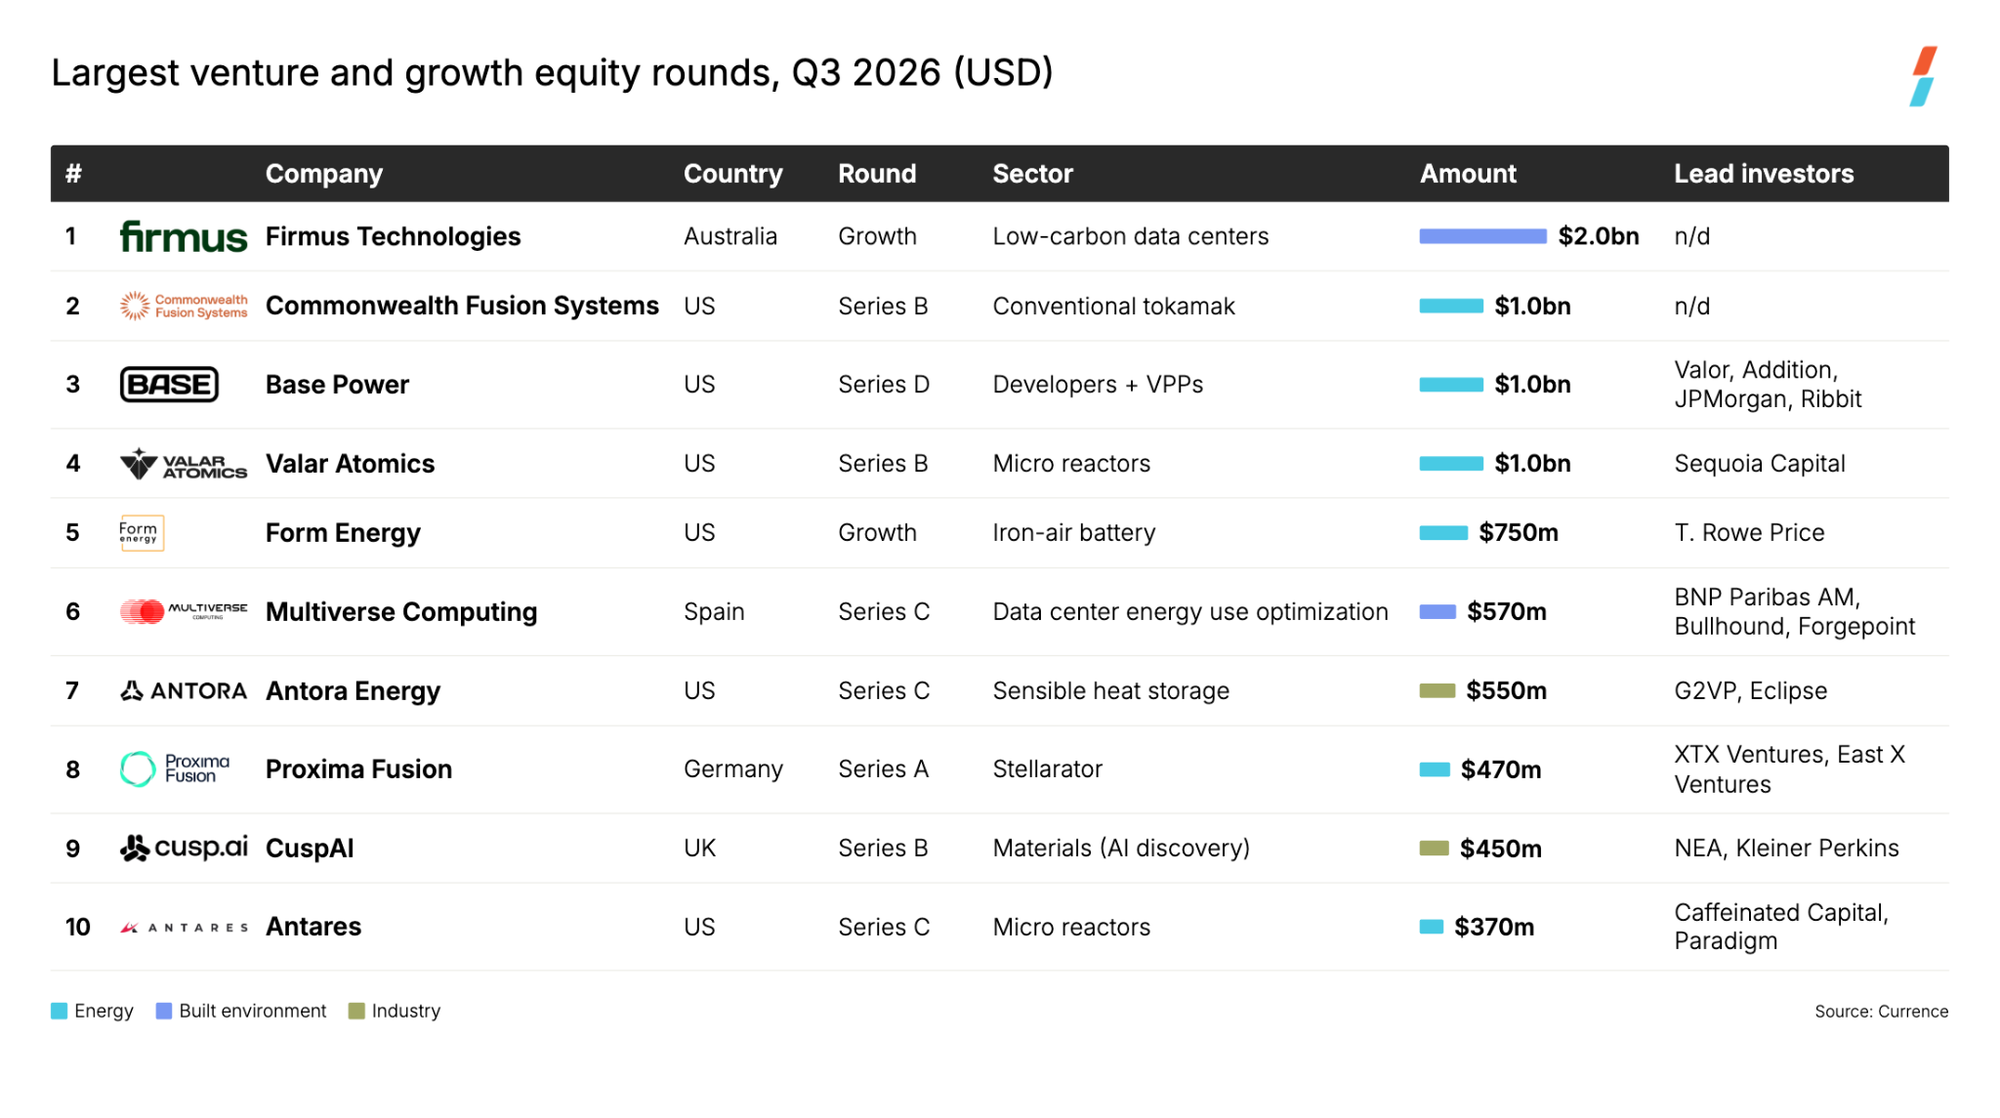
Mega deals took 82% of Q3 dollars as deal count fell to its lowest since 2020
Happy Tuesday!
Q4 is in full swing, so we’ve got your Q3 climate tech deals and trends roundup. Our quarterly roundup breaks down where the money went, who exited, and what’s behind all of it.
In deals, $225m for DERs in California; $200m for stellarator fusion in Tennessee; and $110m for superconducting electric transmission in Massachusetts.
In other news, South Korea’s $747bn energy transition plan, a one-year delay for EU methane rules, and a greenlight for one of the largest rare earth deposits outside China.
Thanks for reading!
Not a subscriber yet?
📩 Submit deals and announcements for the newsletter at [email protected].
💼 Find or share roles on our job board here.
CTVC is powered by Currence, market intelligence to power the AI era.
There’s a chill in the air, the leaves are changing, and Q4 is in full swing.
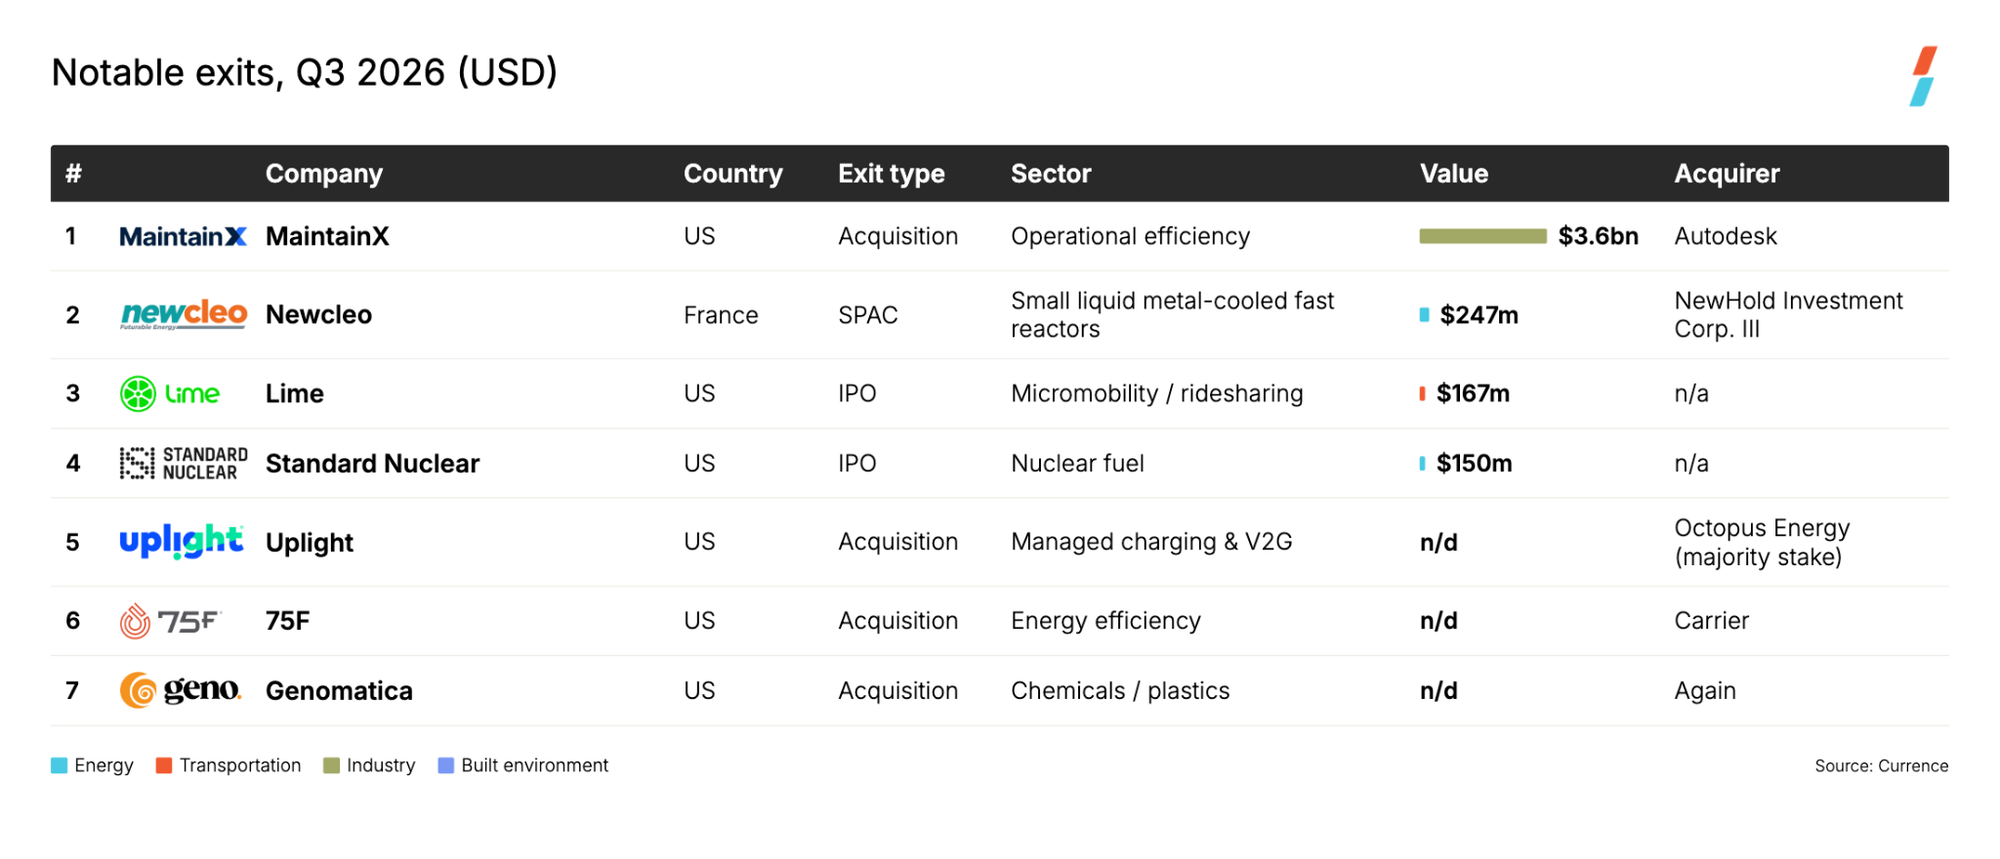
You know what that means: our Q3 climate tech roundup! Currence tracks deals, exits, and investment in real time, and here’s our breakdown of last quarter’s biggest hits. Tell us your take by replying to this email.
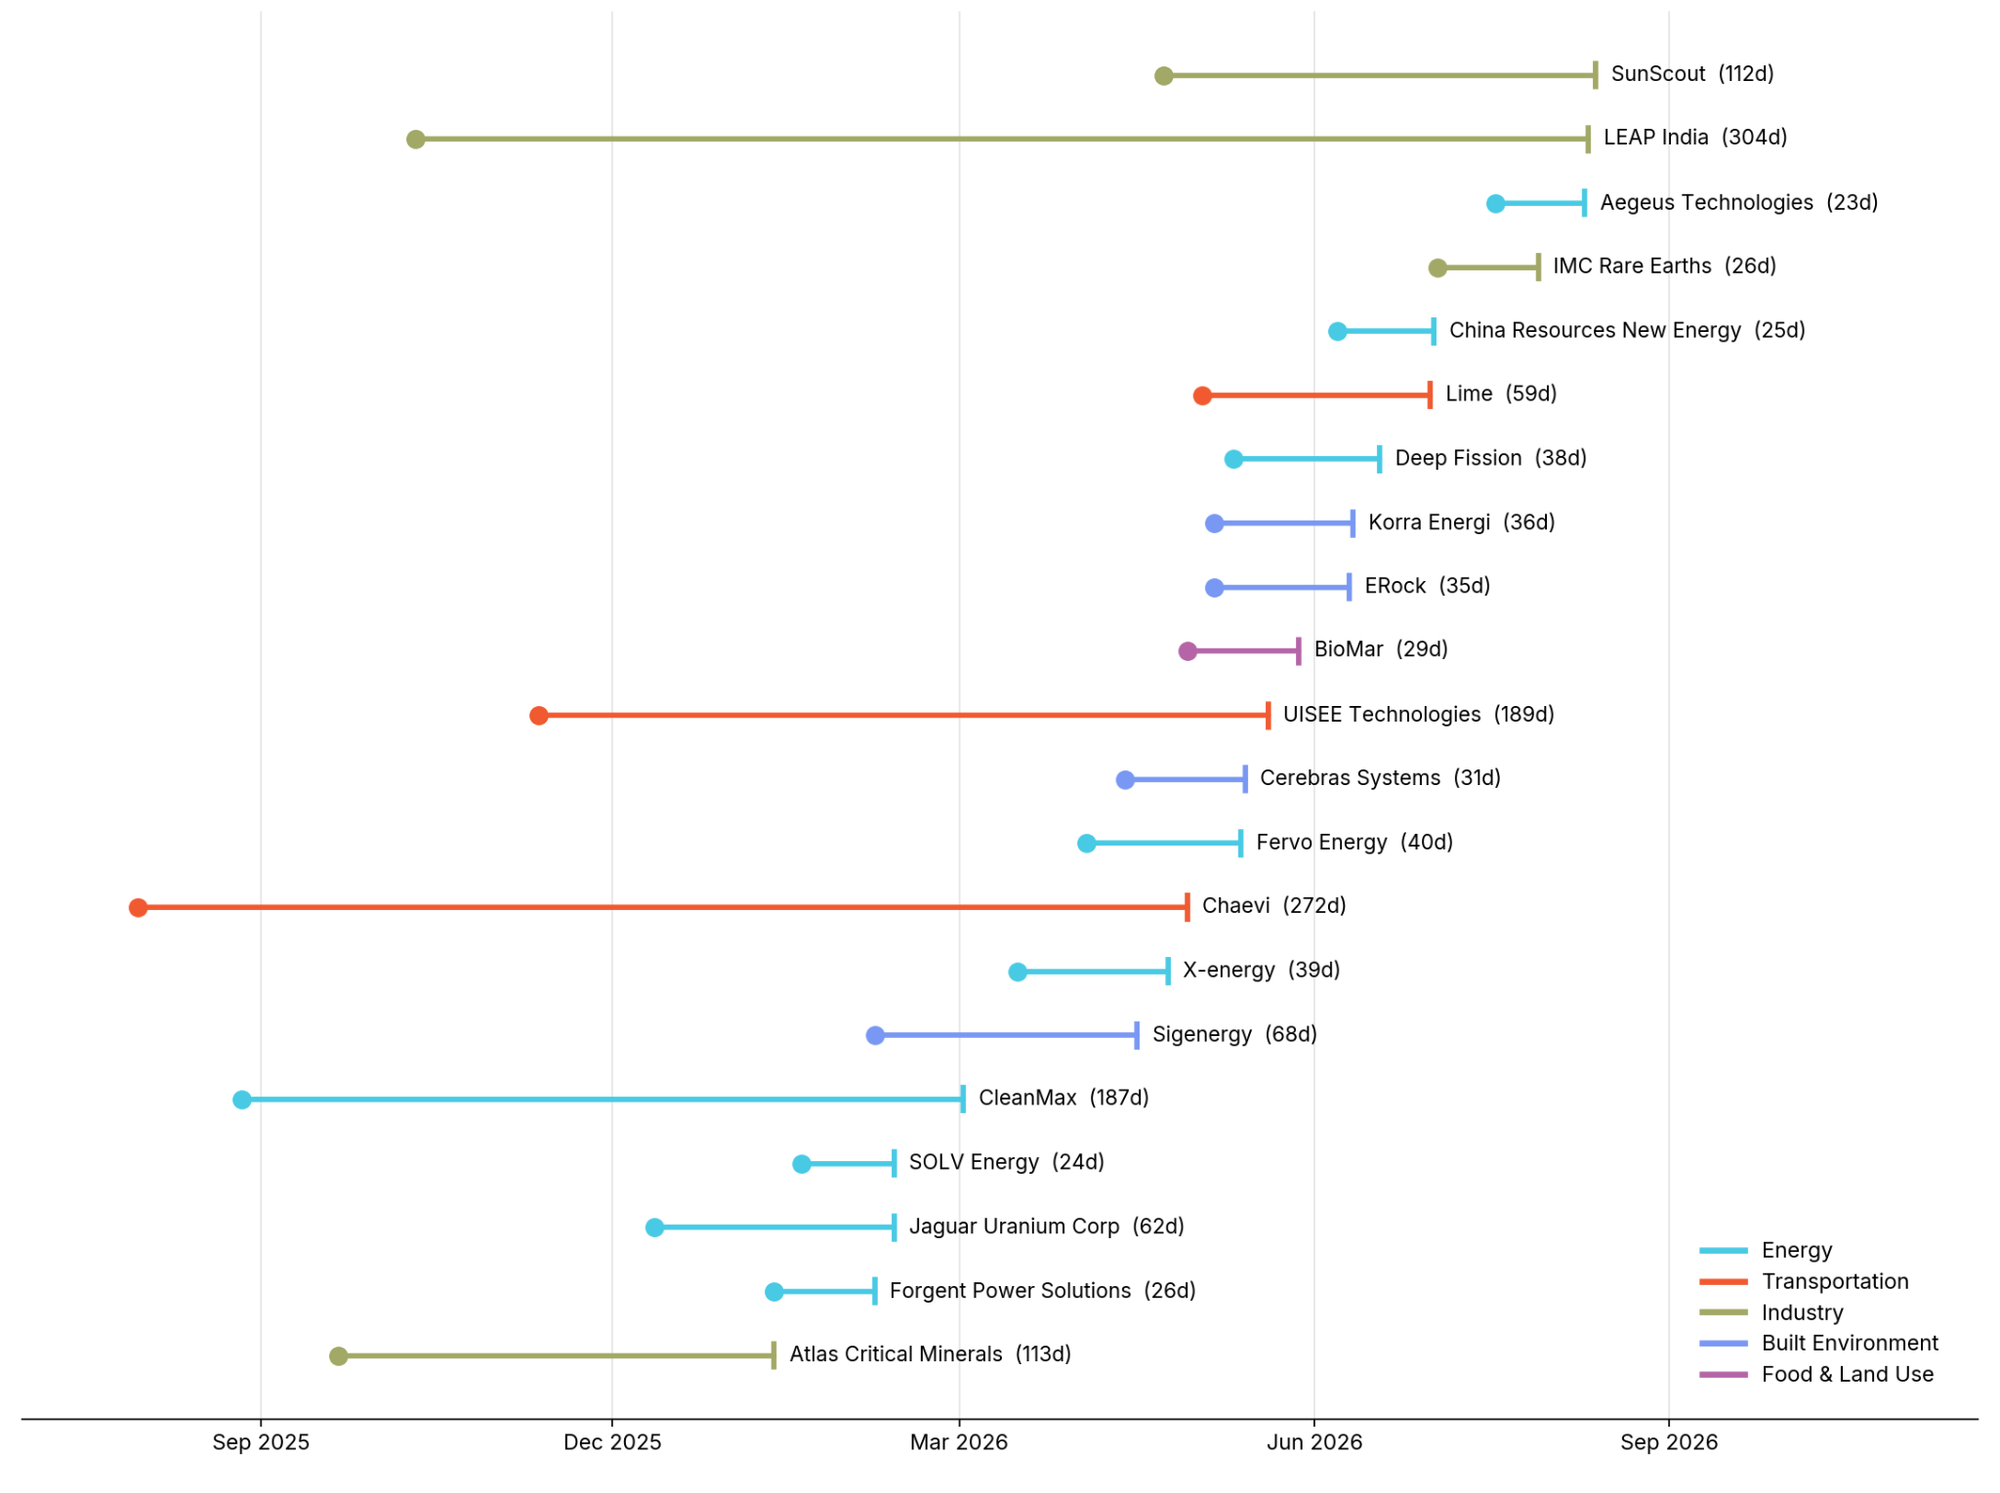
Time from IPO announcement to listing, 2026 IPOs YTD
⚡ Voltus, a San Francisco, CA-based distributed energy resource platform and virtual power plant operator, raised $225m in Series D funding from Generation Investment Management, Activate Capital Partners, Vitol, Ajax Strategies, All Aboard Coalition, and other investors.
⚡ Type One Energy, a Knoxville, TN-based stellarator fusion power developer, raised $200m in Series B funding from Breakthrough Energy Ventures, Clutterbuck Capital, Lowercarbon Capital, Siemens Energy Ventures, and SiteGround Capital.
⚡ VEIR, a Woburn, MA-based superconducting electric transmission developer, raised $110m in Series C funding from Tyche Partners, Matter Venture Partners, Congruent Ventures, Engine Ventures, Galvanize Climate, and other investors.
🚆 Parallel Systems, a Los Angeles, CA-based developer of autonomous battery-electric rail freight vehicles, raised $100m in Series C funding from Atlantic Vantage Point (AVP), Agility, Anthos Capital, Cobalt Capital, Collaborative Fund, and other investors.
⚡ Helical Fusion, a Tokyo, Japan-based helical fusion reactor developer, raised $20m in Series B funding from Fuji Electric, Fujikura, Hazama Ando Corporation, Kepple Group, KKT LLC, and other investors.
🔋 VoltR, an Angers, France-based developer of remanufactured lithium batteries, raised $18m in Seed funding from Bpifrance and Decathlon Pulse.
🧱 Reclinker, a Cardiff, Wales-based low-carbon cement producer, raised $13m in Series A funding from AP Ventures, Clean Growth Fund, Cambridge Enterprise, Development Bank of Wales, Kibo Invest, and other investors.
🌾 BloomX, a Tel Aviv, Israel-based AI-powered robotic crop pollination platform, raised $13m in Series A funding from Elah Fund, Granot Organisation, OurCrowd, and Rothschild & Co.
⚡Mana Battery, a Boulder, CO-based developer of sodium-ion batteries, raised $8.3m in seed funding from Voyager Ventures, Buff Gold Ventures, and Union Square Ventures.
⚡ Blaze Energy Technologies, a Denver, CO-based developer of flex-fuel reformer systems for maritime engines, raised $6.5m in Seed funding from Propeller, Catalyzer Ventures, Cartography Capital, Desai Ventures, Safar Partners, and other investors.
🥩 Edonia, a Bordeaux, France-based microalgae-based protein ingredients producer, raised $5.6m in Seed funding from SWEN Blue Ocean, EIT Food, and Asterion Ventures.
🌾 hexafarms, a Berlin, Germany-based AI-powered greenhouse crop monitoring platform, raised $5.4m in Seed funding from Ananda Impact Ventures, Green Generation Fund, Better Ventures, Grey Silo Ventures, Mudcake, and other investors.
⚡ Neela Biotech, a Cambridge, England-based developer of sustainable aviation fuels from organic waste, raised $2.8m in Pre-seed funding from Elbow Beach Capital, Ascension, Cambridge Enterprise, and Ventures Together.
🌾 Finches, a Munich, Germany-based agricultural sourcing intelligence platform, raised $2.2m in Pre-seed funding from High-Tech Gründerfonds (HTGF), Vanagon Ventures, Bayern Kapital, and UnternehmerTUM.
⚡ Elvy, a Stockholm, Sweden-based provider of home energy subscriptions, raised $1.6m from angel investors.
⚡ Grenergy Renovables, a Madrid, Spain-based renewable energy producer, raised $228m in PF Debt funding from BNP Paribas, Banco Bilbao Vizcaya Argentaria (BBVA), Banco Santander, JPMorgan Chase, MUFG Bank, and other investors.
⚡ ACEN Corporation, a Makati, Philippines-based renewable energy project developer, raised $56m in Debt funding from ING Group.
☀️ MaxSolar, a Traunstein, Germany-based integrated renewable energy infrastructure developer, raised $44m in PF Debt funding from Copenhagen Infrastructure Partners (CIP).
🥩 Edonia, a Bordeaux, France-based microalgae-based protein ingredients producer, raised $5.6m in Debt funding from undisclosed investors.
🏠 Accelergen Energy, an Austin, TX-based renewable power and storage developer, closed a PE Buyout from Fengate Asset Management.
🏠 Rensa Filtration, an Aurora, IL-based commercial air filtration systems provider, closed a PE Buyout from British Columbia Investment Management Corporation (BCI) and AEA Investors.
⚡ Smartcar, a Mountain View, CA-based vehicle data integration platform, was acquired by Everyday Electric for an undisclosed amount.
🔋 10DQ, a Somerville, MA-based long-duration energy storage technology developer, went Out of Business.
🏠 Greenhome Specialties, a West Haven, UT-based provider of energy efficiency services, was acquired by SEI Group for an undisclosed amount.
🌾 NABVENTURES, a Mumbai, India-based venture capital arm of NABARD, closed $51m for the first close of NABVENTURES Fund II, investing in early- and growth-stage agritech, rural fintech, climate-smart agriculture, and food and agribusiness startups.
🌴 Oraseya Capital, a Dubai, UAE-based venture capital firm, closed $272m for the second close of its venture fund, investing in early-stage and Series B+ AI, fintech, digital asset, healthcare and longevity startups connected to the UAE.
This is a sample of deals available for Currence clients. Can’t get enough deals?
🇰🇷 South Korea unveiled a $747bn energy transition plan, targeting 100GW of low-carbon additions by 2030 under the Korean Green Transformation program. The strategy aims to make Korea a top-three green manufacturing power through hydrogen-reduction steelmaking, next-generation solar cells, and all-solid-state batteries. [Link]
This is industrial strategy paired with climate policy, and the sectors chosen are the ones where Korea thinks it can beat China rather than compete head-on. It comes as Seoul advances construction of as many as eight nuclear reactors in the US, six AP1000s and two of their own APR1400s.
🏛 The EU’s energy chief said methane rules for oil and gas will be delayed by a maximum of one year. [Link]
A one-year delay rather than the permanent stop some countries wanted. These rules matter disproportionately because they apply to imported gas, so they reach well beyond EU borders.
✈️ Infinium launched mSAF, extending its platform to methane feedstocks including RNG. [Link]
RNG becomes another feedstock for Infinium’s existing and announced Fischer-Tropsch projects, firming up the supply chain rather than adding new capacity. Feedstock flexibility is how eSAF projects are de-risking against any single input market. Currence clients can read the Q3 2026 Fuels & Carbon Outlook to learn more.
🌬 Global floating wind capacity reached 382MW, per RenewableUK. [Link]
Small in absolute terms, but floating unlocks deep-water geographies that fixed-bottom can’t reach, including the US west coast. California is running a procurement of up to 7.6GW that would have to be mostly floating wind. [CPUC]
⛏ Greenland approved mining plans for Critical Metals’ Tanbreez project, one of the largest undeveloped heavy rare earth deposits outside China, with $2.1bn estimated total value and $290m of initial capex. [Link]
🛢 Brent crude is jumping again, nearly 5% to more than $106, with upward pressure from Trump weighing escalation in Iran, continued attacks on Middle East shipping, and Hurricane Isaias shutting US Gulf production. [Link]
🔋 Antora announced its Pratt project, a repeat of its 5GWh thermal storage design with equity finance from CIP and UPP. [Link]
💧 France set out penalties for fuel suppliers failing to meet clean hydrogen mandates, following Germany’s move in August. [Link]
🛰 The FCC is shortening satellite approval timelines as part of a broader deregulation push, and moving environmental scrutiny of launch, debris removal, and reentry onto the FAA. It approved 15,000 new Starlink satellites for direct-to-mobile connectivity this week. [Link, Link]
🌡 The Climate Brink on the impacts of this year’s record El Niño. [Link]
🚗 Suzuki built its first electric kei car on BYD batteries and undercut BYD’s cheapest mini EV at about $13,500, a way to win a price war against your own supplier. [Link]
📣 Cradle to Commerce (C2C): Pre-application for the program’s Legion teams, open to startups, entrepreneurs, and technologists. Selected participants’ responses will be shared with C2C’s coaches, mentors, and partner organizations. Applications due November 15.
💡 Breakthrough Energy Fellows: Full-time 12-month fellowship for early-stage clean-tech founders with up to $500K in catalytic funding via SAFE. Open globally. Applications due November 2.
📅 Greentown Labs Climatetech Summit: Greentown's flagship regional summit for climate hardware founders, investors and corporates, on October 29 in Boston. Register before tickets run out or join virtually for free.
Account Executive @Currence
Data Product Manager @Currence
Founding Customer Success Manager @Currence
Senior Backend Engineer (AI) @Currence
Director of Growth & Giving @Elemental Impact
📩 Feel free to send us deals, announcements, or anything else at [email protected]. Have a great week ahead!

 Newsletter