


🌎 Q3 roundup ft. mega deals, nuclear listings, and more #317
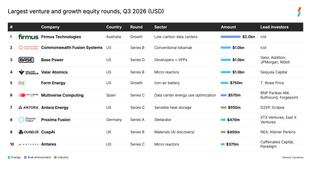
Mega deals took 82% of Q3 dollars as deal count fell to its lowest since 2020
Happy Monday!
We're taking a Eurotrip and diving into a new report from AENU, built on Currence data, that traces who actually builds Europe’s best-funded climate companies. We compare them with their US counterparts below.
In deals, $298m for salt-cooled high-temperature nuclear reactors in California; $78m for smart energy systems in Hamburg; and $70m for disaster-exposed property insurance in California.
In other news, the DOJ moves to reopen Revolution Wind’s approval, steep new solar cell tariffs on India and Southeast Asia, and geothermal wins rare bipartisan love.
Thanks for reading!
Not a subscriber yet?
📩 Submit deals and announcements for the newsletter at [email protected].
💼 Find or share roles on our job board here.
CTVC is powered by Currence, market intelligence to power the AI era.
In the US, the climate tech founder stereotype is Tesla mafia or a Stanford MBA. That’s not the case in Europe. Our friends at AENU, a Berlin-based early-stage VC investing in energy transition, industrial transformation, and resilience tech, just released a report using market data from Currence 😉 to see who actually builds Europe’s biggest climate companies, and how they got there.
Check out the really cool interactive version of AENU’s The Execution Game here and download the report there, or read on for more!
The team traced the careers of the founders behind Europe’s 100 best-funded climate companies, each of which had raised at least €50m, then ran the same analysis on 100 US founders for comparison. (You can see all the companies in the report.) They also interviewed ten company leaders, including the founders of Tokamak Energy, Wallbox, and Sunly, and named 20 “Tomorrow’s Champions” to watch.
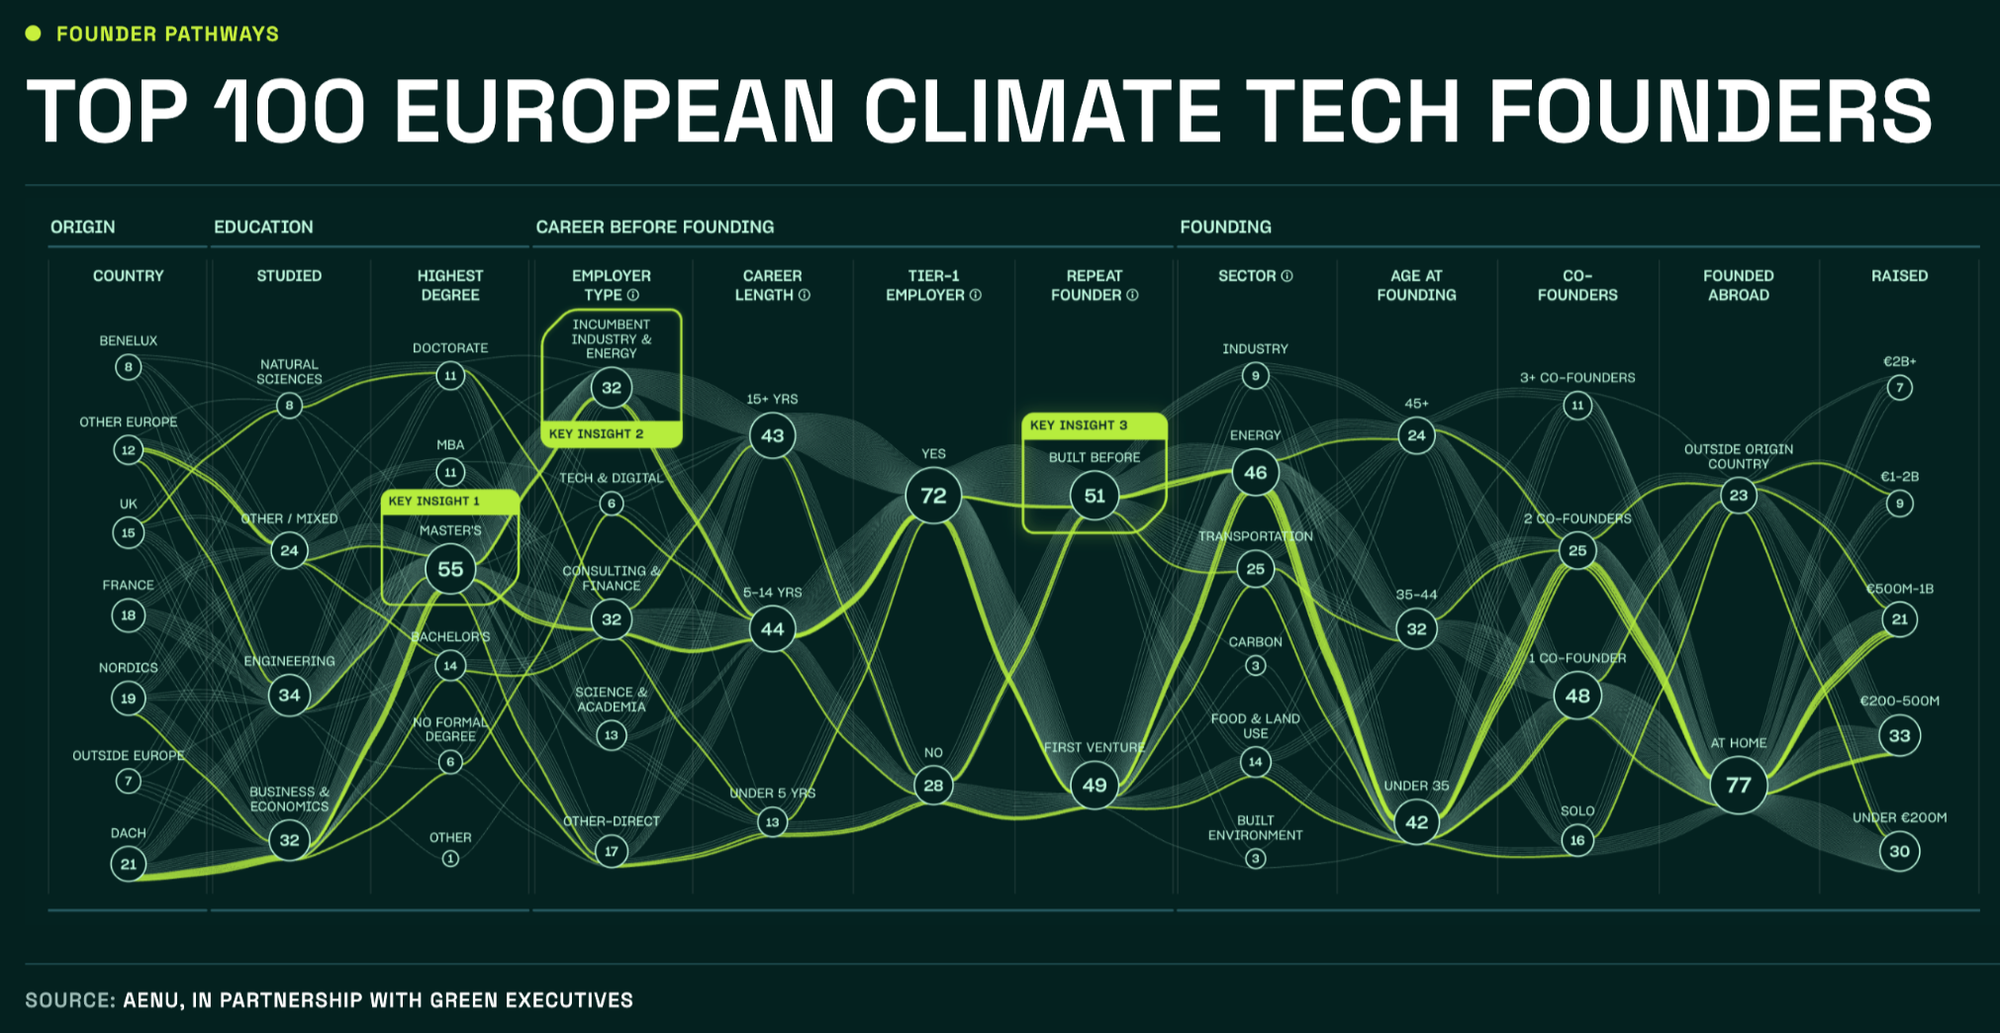
The US and Europe are the two most developed markets for climate tech VC, and investors constantly compare where the capital is going, how fast deals close, which region builds faster. AENU’s report helps explain why the same technologies scale differently on each side of the Atlantic, and reveals what the next generation of founders could look like.
The sharp split is at growth funding. Many European companies aren’t leaning on equity. Elvy, which sells Swedish homeowners solar, heat pumps, and batteries on a fixed monthly subscription, raised a roughly $585m debt facility against under $12m of equity. Cloover, a Berlin-based financing platform for home energy installers, paired a $22m Series A with more than $1.3bn in debt backed by a European Investment Fund guarantee. Hometree founder Simon Phelan, who closed the UK’s first residential renewable securitization, says he’d take venture much later if he did it again.
That tracks with our own 2026 Founder Survey with Elemental Impact, in which 73% of founders flagged capital structure as a top financing challenge. Traditional VC wasn’t built for capital-intensive, long-horizon projects, so nearly half (47%) said non-dilutive grants would accelerate their growth, and 29% pointed to blended finance.
⚡ Kairos Power, an Alameda, CA-based developer of fluoride salt-cooled high-temperature nuclear reactors, raised $298m in Growth funding from Google Ventures and DCVC.
⚡ 1Komma5°, a Hamburg, Germany-based provider of residential smart energy systems, raised $78m in Growth funding from b2venture, Marunouchi Innovation Partners, Blue Elephant Ventures, eCapital, Eurazeo, and other investors.
☔ Stand, a San Francisco, CA-based insurance provider for disaster-exposed properties, raised $70m in Series C funding from Saga Ventures, Eclipse, Equal Ventures, Inspired Capital, Jackson Square Ventures, and other investors.
⚡ Rabot Energy, a Hamburg, Germany-based digital electricity supplier offering dynamic tariffs, raised $56m in Series B funding from Endeit Capital, Acurio Ventures, Bosch Ventures, CNI, DeepTech & Climate Fonds (DTCF), and other investors.
🔋 Holyvolt, a Stockholm, Sweden-based developer of an AI-powered battery materials discovery platform, raised $45m in Series A funding from Course Corrected VC and Zone II Ventures.
⚡ Switched Source, a Chicago, IL-based developer of power-flow control technology for distribution grids, raised $17m in Seed funding from Cubit Capital, ABB, Emerald Technology Ventures, Red Cedar Ventures, Southern States, and other investors.
🏭 EPYR, a Paris, France-based industrial thermal energy storage developer, raised $17m in Series A funding from Slate Venture Capital, AENU, Aurum Impact, Daphni, OVNI Capital, and other investors.
⚡ HyLight, a Le Plessis-Pâté, France-based operator of hydrogen-powered autonomous airships for infrastructure inspection, raised $15m in Series A funding from Rubio Impact Ventures, DRW, Ring Capital, Teampact Ventures, and Y Combinator.
💨 CarbonFarm Technology, a Paris, France-based rice decarbonization MRV and project development platform, raised $8m in Series A funding from Colam Impact, Albo, Bpifrance, Makesense, Proparco, and other investors.
🔋 NEU Battery Materials, a Singapore-based lithium iron phosphate (LFP) battery recycling platform, raised $8m in Seed funding from SGInnovate, Shift4Good, Lotus Singapore, M7 Holdings, and Paragon Capital Management.
⚡ RX, a Daejeon, South Korea-based developer of heat-supply small modular reactors for industry, raised $8m in Seed funding from Kiwoom Securities, Korea Development Bank, K Partners, and Smilegate Investment.
⚒️ Giraffe Bio, a Buenos Aires, Argentina-based developer of AI-designed biomolecules for copper flotation, raised $6m in Seed funding from Orion Industrial Ventures, Air Capital, BHP Ventures, Baruch Future Ventures, and Twynam.
♻️ Ambio, a Helsinki, Finland-based recycled plastics procurement platform, raised $6m in Seed funding from b2venture, Lifeline Ventures, and Montis VC.
🌾 OlsAro, a Göteborg, Sweden-based developer of climate-resilient cereal genetics, raised $6m in Seed funding from Industrifonden, Nordic Foodtech VC, AgFunder, Future Food Fund, GU Ventures, and other investors.
🌾 Molagri, a Toronto, Canada-based developer of precision biopesticides, raised $5m in Seed funding from Convective Capital, Robinhood, Superorganism, and Y Combinator.
🏠 DayOne, a Singapore-based developer and operator of low-carbon data centers, raised $3.7bn in Debt funding from CIMB, Crédit Agricole Corporate and Investment Bank (CIB), DBS Bank, Maybank, and other investors.
🔋 Flatiron Energy, a Boulder, CO-based utility-scale energy storage developer, raised $510m in PF Debt funding from Banco Santander, East West Bank, Investec, Norddeutsche Landesbank (Nord/LB), Siemens Financial Services, and Société Générale.
⚡ Deriva Energy, a Charlotte, NC-based developer and operator of renewable energy assets, raised $280m in PF Debt funding from Canadian Imperial Bank of Commerce (CIBC) and KeyBank Capital Markets.
🛰 Fugro, a Leidschendam, Netherlands-based geo-data services provider, raised $168m in Post-IPO Debt from European Investment Bank (EIB).
⚡ Concord New Energy Group, a Singapore-based developer and operator of renewable power and energy storage projects, raised $155m in PF Debt funding from Associated Bank, First Citizens Bank, and Goldman Sachs Asset Management.
⚡ New Brunswick Power, a Fredericton, Canada-based electric utility in New Brunswick, raised $154m in PF Debt funding from Canada Infrastructure Bank (CIB).
⚡ ReNew, a Gurgaon, India-based renewable energy producer, raised $100m in Debt funding from FMO (Dutch Entrepreneurial Development Bank).
💧 Connexin, a Kingston upon Hull, England-based provider of IoT solutions for smart infrastructure, raised $33m in Debt funding from Banco Santander and Patrizia.
🏠 Cold Solutions Rwanda, a Kigali, Rwanda-based provider of cold chain logistics, raised $18m in PF Debt funding from AfricaGoGreen Fund (AGoGF).
⚒️ CoTec Holdings, a Vancouver, Canada-based developer of critical-mineral extraction and recycling technologies, raised $14m in Post-IPO Debt from undisclosed investors.
🛵 Envoy Technologies, a Culver City, CA-based electric car sharing platform, was acquired by Dot Ai at an implied valuation of $65m.
🔋 FlowCellutions, a Pittsburgh, PA-based developer of monitoring and diagnostics tools for flow battery energy storage systems, was acquired by Terraflow Energy for an undisclosed amount.
🌾 PickTrace, a Los Angeles, CA-based farm workforce management software platform, closed a PE Buyout from Terminus Capital Partners.
🥩 Daisy Lab, an Auckland, New Zealand-based precision fermentation platform for dairy-identical proteins, was acquired by Mycofeast for an undisclosed amount.
⚡ Zembl, a Sydney, Australia-based energy procurement and management services provider, closed a PE Buyout from TPG.
☀️ Bold Renewables, a Windsor, CO-based solar inverter field service provider, was acquired by Integrated Power Services for an undisclosed amount.
This is a sample of deals available for Currence clients. Can’t get enough deals?
💨 The Justice Department asked a federal court to send Interior’s approval of Revolution Wind back for review, putting at risk Orsted’s 704MW offshore wind farm, which has fed power to the Northeast grid since March and installed its last turbine in September. Interior wants to reevaluate whether its 2023 sign-off complied with federal offshore leasing law. [Link]
Offshore wind has been a Trump political target for years. This filing came shortly after Trump agreed to free up 30 stalled wind projects as part of the Senate permitting deal, whose lead Democrat, Sen. Whitehouse, represents Rhode Island, calling the deal into question.
☀️ In tariff news, the US International Trade Commission ruled that solar cells from India, Indonesia, and Laos hurt US manufacturers, clearing the way to issue duty orders in early November. Combined rates could reach about 268% for Indonesia, 249% for India, and 219% for Laos, on top of existing tariffs. [Link]
Indian and Southeast Asian cell capacity filled the gap after earlier duties hit China. Meanwhile, China’s five largest solar makers cut 40,589 jobs last year as they lost money on rising sales. US developers racing the end-of-2027 placed-in-service deadline for 48E and 45Y will pay more for cells while the global glut deepens.
🔋 Battery storage failures fell 98% per GWh from 2018 to 2025, with stationary systems now failing at 0.04% to 0.14% a year and no US BESS injuries or fatalities reported since April 2019. [Link]
Systems commissioned before 2021 make up 3% of global capacity and carry most of the explosion risk. Community opposition remains after high-profile fires, though, so developers will have to emphasize safety where storage projects keep stalling.
💰 Affordability is driving electrification, from heat pumps to EVs. Canada announced a National Heat Pump Rebate as part of a CAD 2bn (about $1.4bn) plan to retrofit 1m homes over eight years, and US EV sales may be starting to rebound. [Link, Link]
Canada’s rebate covers up to 820,000 households, with CAD 10,000 for below-median-income households and CAD 2,000 for everyone else. The eight-year commitment gives installers a horizon to hire and stock up. In the US, EVs hit 6.5% of new car sales in Q3, their best quarter since the federal tax credit ended last fall, with gas above $4 a gallon driving the market.
💦 A new study finds US households’ drinking water costs are climbing, rising 62% from 2015 to 2025, outpacing both inflation (39%) and grocery prices (30%). [Link]
Water affordability is following the same trajectory as electricity bills, and for overlapping reasons: aging infrastructure, increasing demand, climate stress, and deferred capex all landing on the ratepayer.
🌋 Geothermal has found rare bipartisan support in Washington. The Senate permitting bill gives it more help than wind or solar, and the House passed several of the same provisions this summer with sponsors from AOC to Utah Republican Mike Kennedy. Currence data shows the average winning bid for federal geothermal leases jumped from $10 an acre in 2023 to $182 this year. [Link]
🪨 Frontier made its first purchase of in-situ mineralization, buying $11.7m of removal from 44.01, which injects CO2 into peridotite rock in the UAE to turn it to stone. [Link, read more about Frontier’s newest thesis in CTVC here.]
☀️ Qcells aims to build the world’s first large-scale factory for next-gen tandem solar, as the race to finally scale perovskite-silicon tandem continues. [Link]
🔋 China is getting in on compressed CO2 storage. [Link]
🎬 BBC Earth and Speed & Scale launched Fixing the Planet, a digital series on climate progress. New short films premiere weekly on YouTube through March 2027. [Link, Link]
📅 Greentown Labs Climatetech Summit: Greentown's flagship regional summit for climate hardware founders, investors, and corporates, on October 29 in Boston. Register before tickets run out or join virtually for free.
💡 Breakthrough Energy Fellows: Full-time 12-month fellowship for early-stage clean-tech founders with up to $500K in catalytic funding via SAFE. Open globally. Applications due November 2.
📅 DERVOS 2026: Join the DER Task Force for the fifth annual DERVOS in Brooklyn on November 5. With the overall theme "Everything is DERs", they’re not saying that everything is small, or even literally “distributed,” but that the center of gravity is shifting toward energy resources that are closer to load and controlled by those who need the power. Sometimes that shift is bottoms-up, sometimes it’s centrally planned, but either way, DERs aren’t the sideshow anymore. They’re the main event. Register to hear all the unfiltered hottakes.
Grid Enhancing Technologies Engineer @Georgia Power
Account Executive @Currence
Data Product Manager @Currence
Founding Customer Success Manager @Currence
Senior Backend Engineer (AI) @Currence
Director of Growth & Giving @Elemental Impact
📩 Feel free to send us deals, announcements, or anything else at [email protected]. Have a great week ahead!
Mega deals took 82% of Q3 dollars as deal count fell to its lowest since 2020
Our Q&A with Fervo COO after Cape Station commercial operation

 Newsletter